08 · One possible future · feasibility study
Entertainment
District.
The Playground.
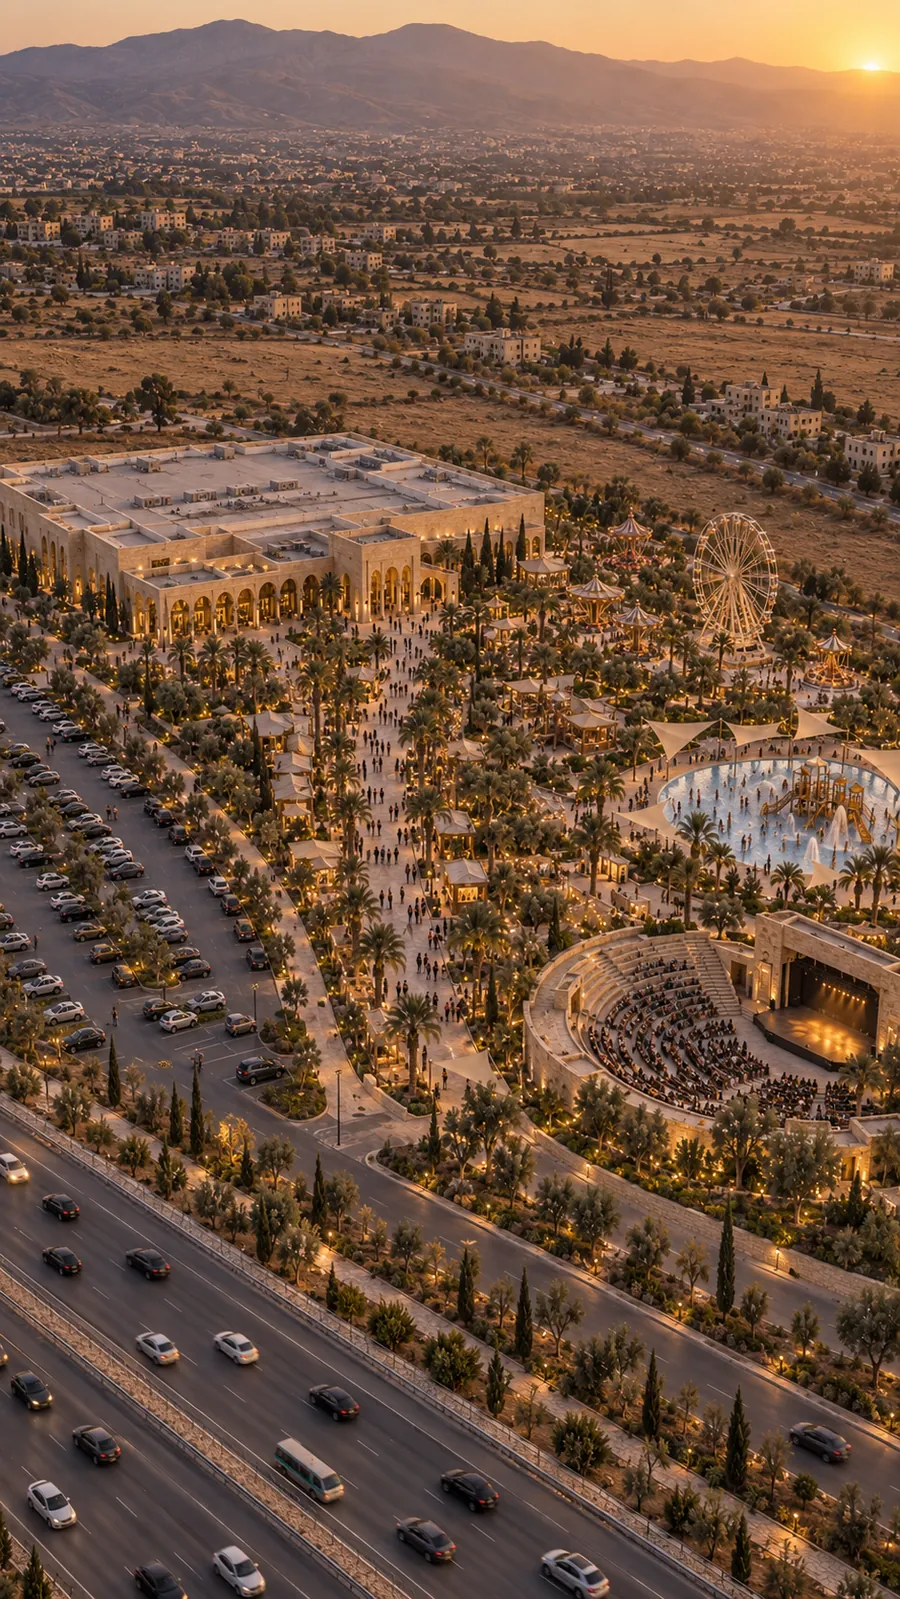
An indoor entertainment centre with an eight-screen cinema, family rides, a splash park, a food street and an open-air arena — for a capital of millions with nowhere modern to spend a family afternoon, studied to feasibility level.
THE IDEA
A capital of millions
with nowhere to play.
Damascus is a city of millions with almost nowhere modern to spend a family afternoon. The Playground study proposes an entertainment district rather than a theme park: ten hectares is the wrong scale for roller-coasters and exactly the right scale for what the city actually lacks — a climate-controlled indoor entertainment centre with an eight-screen cinema, a compact outdoor rides zone for families rather than thrill-seekers, a splash park for the long summer, a food street down the middle, and an open-air arena for concerts, festivals and Ramadan nights.
The site works because of its neighbours: the International Exhibition Centre four kilometres away already draws the crowds, Jaramana and Sayyida Zainab supply the daily families, and the airport road makes the district reachable from every part of the capital — and from the airport in ten minutes.
The study is written for regional leisure operators — the groups that run family entertainment centres and water parks across the Gulf and Egypt — for cinema chains seeking a Damascus flagship, and for family groups that want a visible, cash-generating asset.
WHY NOW
A young city,
coming back to life.
Syria has one of the youngest population profiles in the world, and more than 3.3 million people have returned since December 2024 — families with children and, increasingly, with money earned abroad. Arrivals reached 3.52 million in the first half of 2026 and international card payments returned, which makes cashless ticketing and season passes possible for the first time in fifteen years.
What those families find is old amusement grounds, a handful of tired cinemas and shopping centres with a few arcade machines. Leisure spending is the first discretionary spending to recover in a reopening economy, and it recovers fastest where there is nothing else to spend it on. The first modern entertainment district in the capital takes a market with no competitor.
WHY THIS PARCEL
Five reasons
an operator would choose it.
- The catchment is next door. Jaramana at 1.2 km and Sayyida Zainab at 4 km are among the densest, youngest districts in Syria; central Damascus is a fifteen-minute drive.
- The road. Highway frontage with room for a 1,400-bay car park and coach bays — leisure lives and dies on parking and access.
- The fair next door. The International Exhibition Centre four kilometres away brings a season of visitors the arena and the food street can capture.
- The right size. Ten hectares is too small for a theme park and perfect for an indoor centre, a splash park and an arena — a district that can be built in two phases and expanded.
- Open land, one title. Nothing to demolish; one signature; a name can be announced the day the deal signs.
THE PROGRAMME
What the land
would hold.
| Component | Indicative scale | Note |
|---|---|---|
| Indoor entertainment centre | 14,000 m² GFA | Arcade, VR, indoor rides, bowling, kids’ edutainment; climate-controlled, year-round |
| Cinema multiplex | 8 screens · 5,000 m² GFA | Within the indoor centre; operator-leased |
| Outdoor family rides and games | ≈ 15,000 m² | Carousel, wheel, family rides — not thrill coasters |
| Splash and water park | ≈ 12,000 m² | Summer anchor; shade sails, filtration and recycling |
| Food street, cafés, retail | 6,000 m² GFA | The promenade between the two halves; leased to operators |
| Open-air arena | 5,000 seats · phase 2 | Concerts, festivals, Ramadan programme, graduations |
| Parking and coach bays | ≈ 1,400 bays | Highway side, with drop-off |
| Indicative built area | ≈ 25,000 m² GFA + ≈ 27,000 m² outdoor attractions | Site coverage ≈ 25% — to be tested against zoning and assembly licensing |
Indicative programme for discussion. Ride mix, capacities and licensing must be tested against current zoning, cinema and public-assembly licensing and ride-safety standards before any figure is relied on.
INDICATIVE MASTERPLAN
Indoors and out,
one promenade.
The parcel outline is the source-derived presentation diagram of the supplied survey; the blocks are indicative and drawn for discussion. Phase 1: indoor centre, cinema, rides, splash park, food street, parking. Phase 2: the arena.
THE ROUTES
Three ways
this can be done.
Operator acquires and builds.
A regional leisure group buys the land and builds and operates the district in two phases. It owns a freehold destination with no competitor in the capital and room to expand.
Land-as-equity with an operator.
PETRA contributes Property No. 14 as equity; a leisure investor funds construction; a regional operator runs the district under a management agreement with a performance fee. PETRA holds a share of the only modern entertainment destination in the capital.
Anchor leases, phased build.
The cinema, the food street and the splash park are pre-leased to operators who fit out their own space; the developer builds only the shell, the rides and the promenade, and adds the arena when the first summer proves the numbers. Lowest capital at risk.
WHAT THE OPERATOR GETS
The case
for a leisure group.
- A market with no competitor. The first modern entertainment district in a capital of millions, with the youngest population profile in the region.
- Two seasons, two anchors. The splash park carries the summer, the climate-controlled centre and cinema carry the winter — the year is covered.
- Parking and access. 1,400 bays and coach drop-off on a highway — the operational constraint that kills city-centre leisure schemes.
- An events calendar. The arena, the fair four kilometres away, Ramadan nights, graduations and concerts — revenue that needs no rides.
- A partner, not just a landlord. PETRA is prepared to take equity rather than cash.
RISKS AND MITIGANTS
What could
go wrong.
| Risk | Mitigant |
|---|---|
| Permitted use for leisure and public assembly; cinema, ride and event licensing | Confirm permitted use and licensing before any commitment; phase the arena, which carries the heaviest assembly requirements, into phase two. |
| Visits are untested | Phase one sized at 1.6M visits with season passes and school programmes; anchor leases (Route C) transfer part of the risk. |
| Household spending power and seasonality | Tiered tickets, season passes, Ramadan and school-holiday programming; the indoor centre covers winter and the splash park summer. |
| Water supply and treatment for a splash park | On-site filtration and recycling designed in; storage; capacity letters before commitment — this is the single biggest technical constraint. |
| Ride safety, insurance and management standards | Operator-led procurement to international ride-safety standards; third-party inspection; insurance in place before opening. |
| Traffic on peak evenings and event nights | Access consent with the roads authority; deceleration lane, coach bays, 1,400 bays on site, staged egress after arena events. |
| Political and compliance risk; targeted sanctions remain | Counterparty screening; international arbitration; political-risk insurance where available. |
SOURCES
Where the figures
come from.
- UNHCR, March 2026 — over 3.3M refugees and IDPs returned since Dec 2024; Syria has one of the youngest population profiles in the world. ↗
- The National, 26 Aug 2026 — visitor arrivals 3.52M in H1 2026; international card payments returning (ticketing and cashless operations). ↗
- SANA, 29 Aug 2026 — 63rd Damascus International Fair, ~1,000 entities from 60 countries, at the International Exhibition Centre 4 km from the site. ↗
- Arab News, 12 May 2026 — first Syrian-UAE Investment Forum; tourism, services and leisure among target sectors. ↗
- World Bank, Oct 2025 — Syria reconstruction estimate US$216BN; household spending recovering from a low base. ↗
- U.S. Department of State — comprehensive sanctions revoked June 2025; Caesar Act repealed December 2025 (ride equipment, cinema licensing, international operators). ↗
Nothing on this page is an offer or investment advice. Independent legal, planning, technical and financial review is required.
FOR LEISURE OPERATORS AND CINEMA GROUPS
Read the full
feasibility study.
The asset, the corridor, the market, the programme, the masterplan, three deal routes, risks and the diligence sequence.