02 · One possible future · feasibility study
Residential
Development.
The Return.
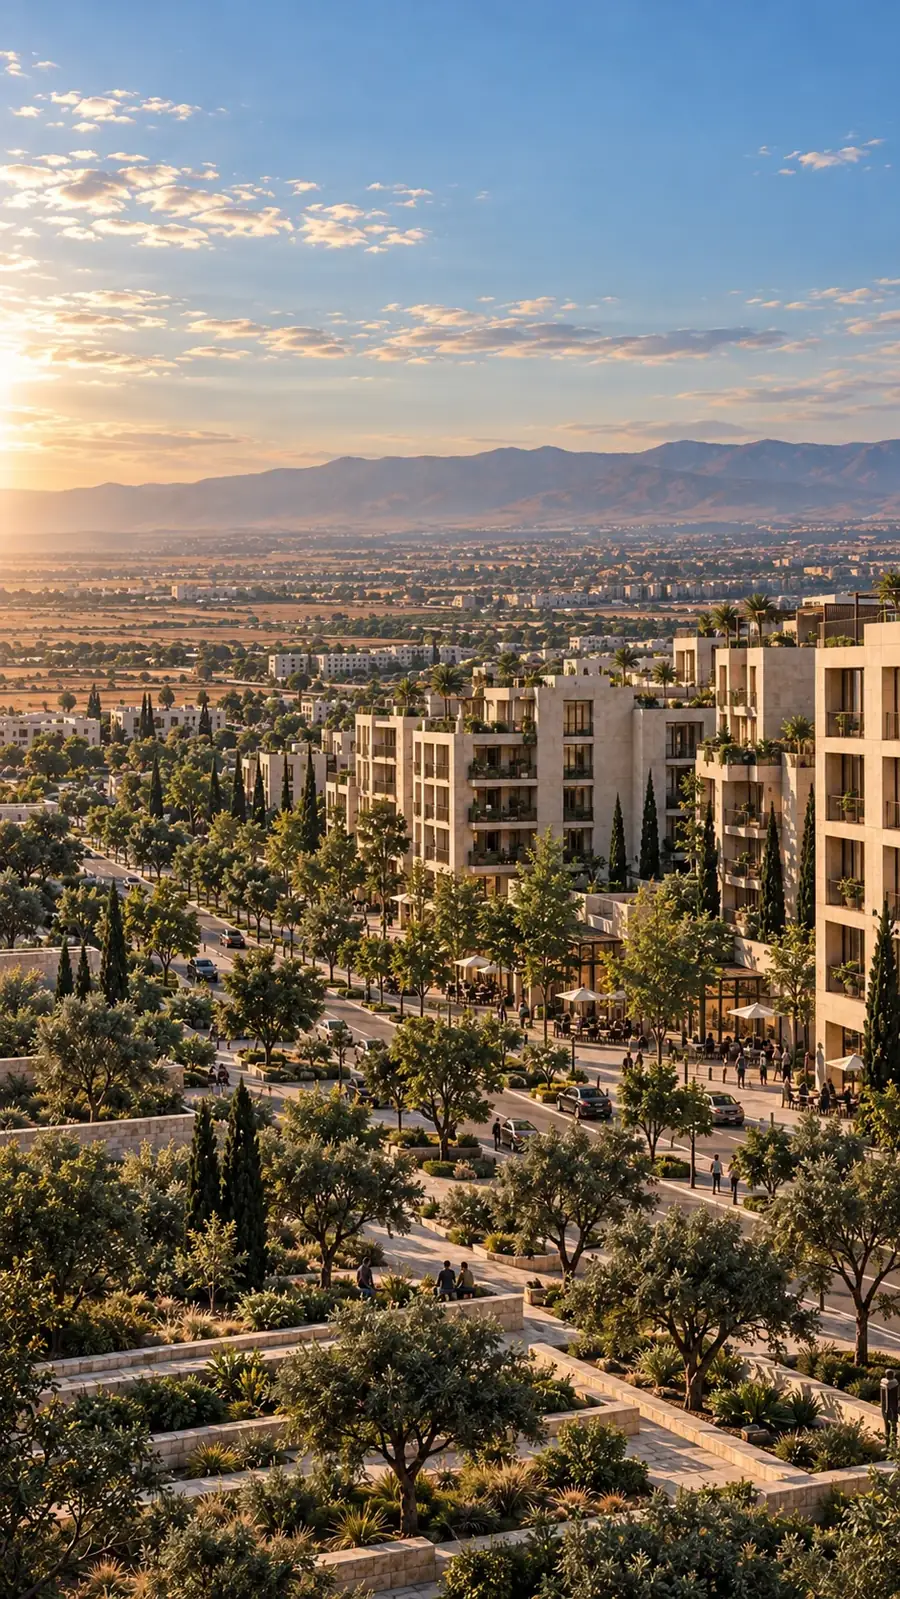
A humane, landscaped neighbourhood of about 950 apartments around shaded courtyards — housing for a city whose people are returning, studied to feasibility level for developers and diaspora capital.
THE IDEA
A neighbourhood,
not a compound.
Syria’s people are coming home to a capital short of homes. The Return study proposes a neighbourhood rather than a gated tower estate: seven courtyard blocks of four to six storeys around shaded courts, a central garden spine, a school, a clinic and a mosque at the heart, and a retail street along the highway that buffers the homes from the road and gives the district its shopfront.
About 950 apartments from one to four bedrooms, so that a whole community can live here rather than one income band. Ten hectares is large enough for a neighbourhood with its own services and small enough for one developer to build in three phases — and it comes as one title, which in Damascus is the rarest thing of all.
The study is written for three kinds of counterparty: a residential developer with delivery capacity in the Levant, diaspora-backed capital looking for a titled, serviced product to sell to returning families, and an institution building housing for its own people.
WHY NOW
The demand
is walking home.
Since December 2024 more than 1.5 million refugees and 1.8 million internally displaced Syrians have returned, according to UNHCR; 5.5 million remain displaced inside the country and 3.9 million registered refugees remain in the region. Return concentrates where it is safe and where services exist — Damascus and its countryside first. The World Bank puts reconstruction at US$216BN, and housing is the largest damaged sector.
The supply that exists is old stock, informal building and small infill. Modern, titled, serviced neighbourhoods are only now appearing, in the suburbs where land is available. A new, secure, solar-powered neighbourhood seven kilometres from the centre — with a clean title behind every apartment — sits in a gap the market has not yet filled.
WHY THIS PARCEL
Five reasons
a developer would choose it.
- Scale for a real neighbourhood. 101,366 m² carries 950 homes, a school and a clinic — services that make a district sell, and that small infill plots can never offer.
- One title. Every apartment inherits a clean chain of ownership from a single registered property. For diaspora buyers, that is the first question and the deal-breaker.
- Seven kilometres from the centre, next to Jaramana. Close enough for daily life in the city; far enough for gardens, air and parking.
- The highway is an edge, not an intrusion. The masterplan places retail and services along the road as a buffer; the homes face inward to their courts and the garden spine.
- Open land. Nothing to demolish or relocate. Site works can start when permits allow.
THE PROGRAMME
What the land
would hold.
| Component | Indicative scale | Note |
|---|---|---|
| Apartments — 1 bedroom (55–65 m²) | ≈ 190 units | Young couples, returnee singles, rental |
| Apartments — 2 bedroom (85–95 m²) | ≈ 330 units | Core product |
| Apartments — 3 bedroom (115–130 m²) | ≈ 330 units | Families |
| Apartments — 4 bedroom and duplexes (150–180 m²) | ≈ 100 units | Top floors; diaspora buyers |
| Sellable residential area | ≈ 100,000 m² | Average ≈ 105 m² per unit |
| Retail street and services | 6,000 m² GFA | Highway edge; sold or leased |
| School, nursery, clinic, mosque | 8,000 m² GFA | Handed to operators |
| Parking | ≈ 1,150 bays | Basement under blocks |
| Gardens, courts, streets | ≈ 45,000 m² | Roughly 45% of the site |
| Gross floor area above ground | ≈ 130,000 m² GFA | Plot ratio ≈ 1.3 · 4–6 storeys — to be tested against zoning |
Indicative programme for discussion. Unit mix, heights and plot ratio must be tested against current Rural Damascus zoning and any corridor master plan before any figure is relied on.

INDICATIVE MASTERPLAN
Seven courts,
one garden.
The parcel outline is the source-derived presentation diagram of the supplied survey. The blocks are indicative and drawn for discussion. Three phases: blocks A–C with the school; D–E with the retail street; F–G.

THE ROUTES
Three ways
this can be done.
Developer acquires and builds.
A developer buys the land, builds in three phases and sells off-plan. Simple; all risk and all upside with the developer; PETRA exits at closing.
Land for units.
PETRA contributes the land and takes about 30% of the sellable area — roughly 285 apartments — delivered on completion of each phase. No cash changes hands for land; the developer’s cash goes into construction. PETRA holds a titled, sellable product in a market it knows.
Land-as-equity joint venture.
PETRA contributes the land as equity; a developer and financial partner fund construction; profits are shared pro rata. PETRA shares the sales risk and the upside beyond base.
WHAT THE BUYER GETS
The case
for a developer.
- A product the market lacks: titled, serviced, secure, solar-powered homes with a school in the middle, sold to families who are already returning.
- Phasing that funds itself. Blocks A–C and the school first; off-plan sales of phase one finance phase two.
- Diaspora demand with hard currency. Returnees from the Gulf, Türkiye and Europe buy in dollars and want clean title above all.
- Control of the timetable. Open land, one owner, no assembly.
- A partner, not just a landlord. PETRA is prepared to take units or equity instead of cash.

RISKS AND MITIGANTS
What could
go wrong.
| Risk | Mitigant |
|---|---|
| Zoning does not currently permit residential density of this order | Confirm permitted use, height and plot ratio; test a lower-density scheme (PR 1.0) as fallback; apply through the investment authority one-stop shop. |
| Off-plan financing and buyer credit are thin | Bank partnerships now emerging for suburban projects; diaspora cash buyers. |
| Infrastructure — water, sewage, power for 950 households | On-site sewage treatment and reuse, water storage, rooftop solar with storage; utility capacity letters before commitment. |
| Highway noise and air quality | Retail and services as a buffer along the road; blocks face inward; acoustic glazing on the southern block. |
| Construction cost inflation and import conditions | Local materials where possible; phase the build; lump-sum packages. |
| Political and compliance risk | Counterparty screening; escrow for buyer deposits; international arbitration in JV contracts. |
SOURCES
Where the figures
come from.
- UNHCR Syria Operational Update, March 2026 — over 1.5 million refugees and 1.8 million IDPs returned since December 2024; 5.5 million still internally displaced. ↗
- UNHCR — 2024: 476,000 verified refugee returns and 376,000 IDP returns; UNHCR Multi-Year Strategy 2026–2029 is return-focused. ↗
- IOM / 3RP 2026 — 3.9 million registered Syrian refugees in Türkiye, Lebanon, Jordan, Iraq and Egypt as of December 2025. ↗
- Abyat, Sept 2026 — returnee families driving demand in Damascus and its countryside. ↗
- World Bank, Oct 2025 — Syria reconstruction estimate US$216BN; housing is the largest damaged sector. ↗
- U.S. Department of State — comprehensive sanctions revoked June 2025; Caesar Act repealed December 2025. ↗
Nothing on this page is an offer or investment advice. Independent legal, planning, technical and financial review is required.
FOR DEVELOPERS AND DIASPORA CAPITAL
Read the full
feasibility study.
The asset, the corridor, the market, the programme, the masterplan, three deal routes, risks and the diligence sequence.